Due Diligence Before Buying a Business in the United States: A Checklist for Foreign Buyers
- dimartinolaw
- 0 Comments
- 5 views
- September 21, 2026
Due Diligence Before Buying a Business in the United States: A Checklist for Foreign Buyers
For a foreign investor, buying an existing U.S. business solves the hardest problems of market entry on day one: customers already exist, revenue already flows, staff already know the work, and the years a startup spends proving itself are already behind the company. That is exactly why acquisitions are a favored route for European investors entering the American market, including E-2 treaty investors building a visa case on the business they buy. It is also why the risk is so concentrated: the buyer is not just purchasing what the seller shows, but potentially everything the seller does not show, the lawsuit not yet filed, the contract about to terminate, the trademark the company never actually owned.
Due diligence is the discipline that closes that gap before the purchase price is paid, and in a cross-border acquisition it has to run on two levels at once: the U.S. legal review itself, and the translation of what it finds into decisions a foreign buyer can act on. This guide is the checklist for that process: the asset-versus-stock decision that frames everything, corporate and ownership review, contract review, liability review, real property and leases, the intellectual property audit, how the acquisition structure interacts with E-2 visa eligibility, and why financial due diligence alone does not protect the buyer.
Where the Hidden Risk Actually Sits
The buyer purchases the past as well as the future
Every operating business carries its history with it: the contracts it signed, the employees it classified, the taxes it collected or did not, the disputes it created. Depending on how the acquisition is structured, some or all of that history transfers with the business. Sellers present the future. Due diligence examines the past, because the past is what the buyer may be inheriting.
The information asymmetry is the whole problem
The seller knows the business completely, and the buyer knows what the seller has chosen to share. Due diligence exists to close that asymmetry through documents, searches, and verification, and the purchase agreement then allocates whatever risk remains through representations, warranties, and indemnities. The two work together: what diligence cannot verify, the contract must cover, which is one reason the legal review and the deal documents should be in the same hands.
Asset Purchase or Stock Purchase: The Decision That Frames Everything
The asset purchase
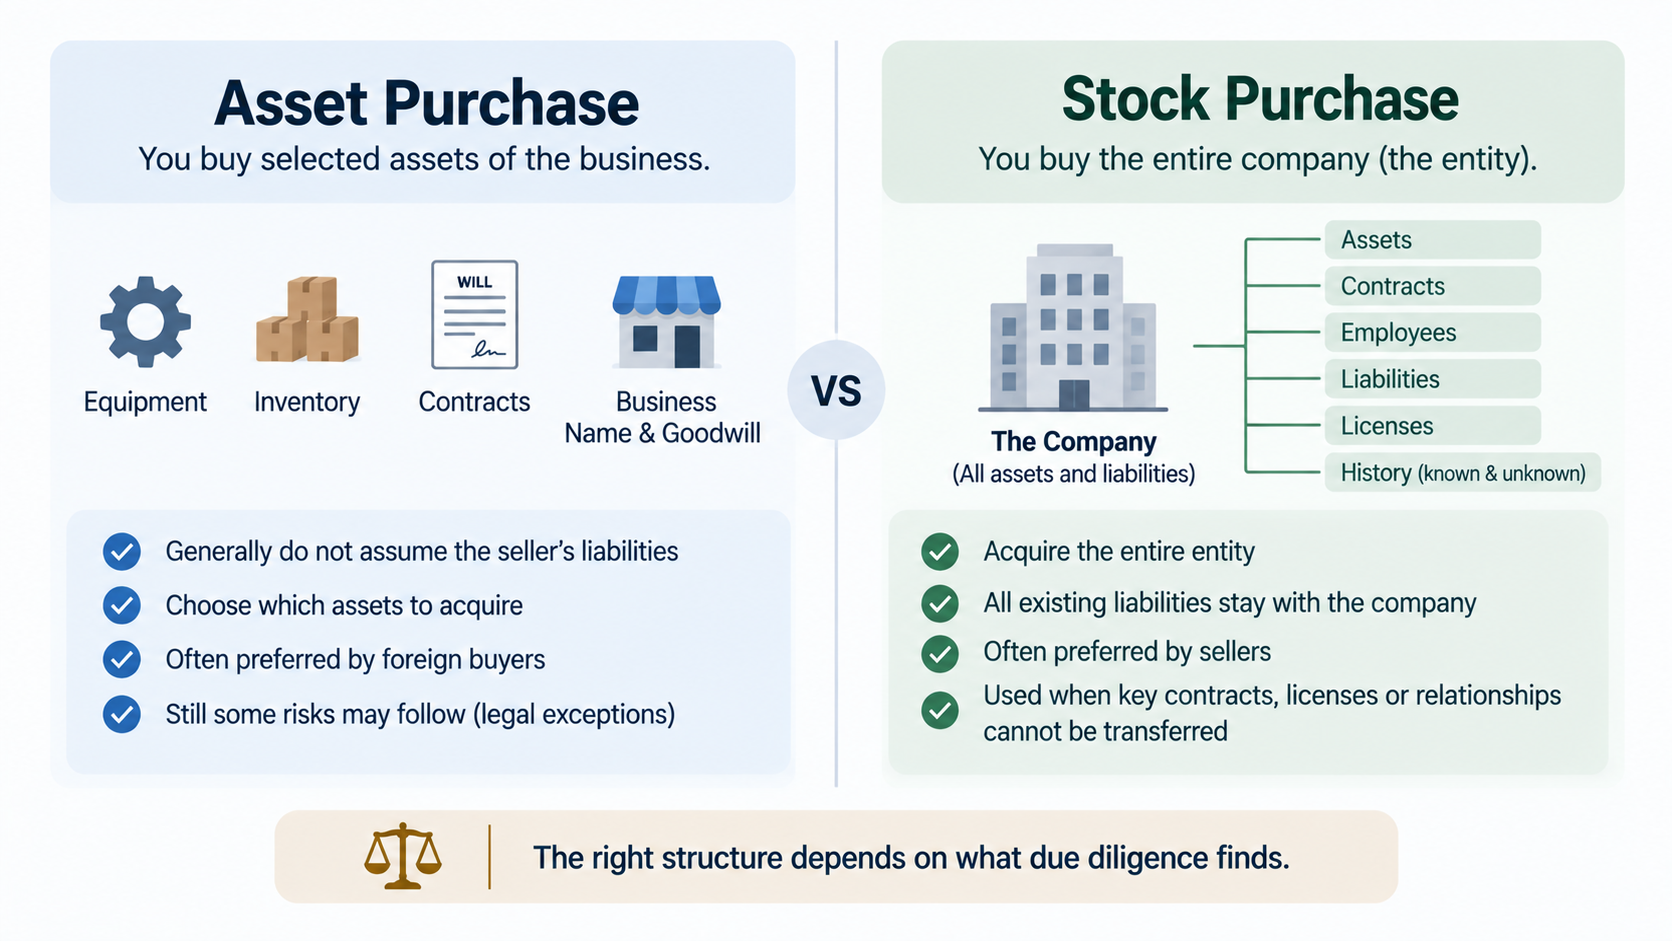
In an asset purchase, the buyer acquires selected assets of the business, the equipment, contracts, inventory, name, and goodwill it chooses, through a new or existing entity of its own, and generally does not assume the seller’s liabilities except those it agrees to take. This is why buyers, and especially foreign buyers without appetite for unknown U.S. liabilities, usually prefer the asset structure. The protection is strong but not absolute: U.S. law recognizes exceptions under which certain liabilities can follow the business to the new owner regardless, which is precisely what the liability review below is designed to surface.
The stock purchase
In a stock or equity purchase, the buyer acquires the entity itself, and the entity keeps everything it has: every contract, every license, every liability, known and unknown. Sellers prefer it for its cleanliness. Sometimes the business itself demands it, where key contracts, licenses, or relationships cannot be transferred and the entity must stay intact. When the structure is a stock purchase, diligence and contractual protections stop being important and become everything, because there is no legal line between the buyer and the company’s past.
The checklist begins with the structure
Which structure fits depends on what diligence finds: clean companies can be bought whole, complicated ones argue for asset deals, and non-assignable contracts can force the question. This is why structure is decided with diligence, not before it, and why the tax treatment of each structure, which differs materially for both sides, should be assessed with the buyer’s tax advisors in parallel with the legal analysis.
Corporate Due Diligence: Is the Seller What It Claims to Be
Entity, standing, and ownership
The foundation checks come first: that the selling entity validly exists and is in good standing where it is formed and where it operates, that the people selling actually own what they are selling, with a clean ownership record and no undisclosed holders, options, or transfer restrictions, and that no consents are missing from anyone whose approval the governing documents require. Lien searches against the company and its assets belong here too, because assets pledged to a lender do not transfer free simply because a purchase agreement says so.
Governance records and approvals
The corporate records, formation documents, governing agreements, minutes, and consents, show whether the company has been run with the formalities its structure requires, and they reveal the approval chain the sale itself must follow. A seller whose own records cannot demonstrate authority to sell is not a smaller problem for being discovered early, but it is a cheaper one.
Contract Review: The Agreements That Are the Business
Reading what the buyer is really acquiring
In most operating businesses, the value sits in contracts: the customer agreements that produce the revenue, the supplier and distribution terms that make delivery possible, the key licenses the operation depends on. Diligence reads them for what they actually say, term and renewal, pricing and termination rights, exclusivity, unusual obligations, because the buyer is stepping into these documents as written, not as summarized by the seller.
Change-of-control and assignment provisions
The single most consequential contract question in an acquisition is whether the agreements survive it. Many U.S. commercial contracts require counterparty consent to assignment, and many contain change-of-control clauses that trigger rights, including termination, when ownership changes, which can apply even in a stock purchase. A business whose three largest customer contracts can be terminated on the sale is worth materially less than its revenue suggests, and the time to know that is before the price is agreed.
Liability Review: What the Buyer Might Inherit
Litigation and regulatory exposure
The checklist here runs from the visible to the latent: pending and threatened litigation, judgments and settlements with continuing obligations, regulatory investigations, licensing and permit compliance in the industry the business operates in, and the disputes that correspondence files reveal before court dockets do.
Employment exposure
Employment is a recurring source of inherited U.S. liability, and foreign buyers routinely underestimate it: worker classification practices, wage and hour compliance in the operating states, California above all, and any agreements or disputes with current and former staff. In an asset deal the buyer’s hiring of the workforce needs its own planning; in a stock deal, the company’s employment history simply continues under new ownership.
Tax exposure
The company’s tax position, federal, state, and local, including obligations a business collects and remits, is part of any liability review, and in some circumstances tax exposure can follow the business itself. The assessment of that exposure belongs with the buyer’s tax advisors, working alongside the legal review. Di Martino Law Group does not advise on tax matters and coordinates with the buyer’s tax advisors so that the legal and tax findings arrive as one picture.
Real Property and Leases
The lease is often the location’s only right
Most acquired businesses operate from leased premises, and the buyer’s entire right to the location is the lease document. Diligence reads it for the term and renewal options, the real rent including pass-through costs, and above all the assignment and change-of-control provisions, because landlord consent is routinely required to keep the premises through a sale, and a landlord’s consent is a negotiation, not a formality.
Estoppels and owned property
Where premises matter to the deal, an estoppel certificate from the landlord, confirming the lease terms, the rent, and the absence of defaults, protects the buyer from inheriting a dispute. Where the business owns real estate, the acquisition absorbs a property transaction inside it, with title, survey, and environmental review of its own, on the standards covered in our commercial property guidance.
The Intellectual Property Audit: Does the Seller Own What It Is Selling
Verification before valuation
The brand, the software, the content, the customer data, the know-how: in many modern businesses this is the asset, and the audit begins with a blunt question, does the seller actually own it. Registrations for trademarks and patents are verified against the public record, in the seller’s actual name, current, and covering the markets that matter, including whether U.S. registrations are matched in the buyer’s other markets, since protection is territorial.
The assignment gap
The classic U.S. finding is the assignment gap: software written by contractors who never signed intellectual property assignments, a logo designed by a freelancer who still owns it, content created before the company existed. Under U.S. law, work created by non-employees does not automatically belong to the company that paid for it, and closing those gaps, with signed assignments, before closing the purchase is the difference between buying an asset and buying a dispute. Trade secrets get parallel treatment: they retain protection only if the company has actually kept them confidential, so the audit examines the agreements and practices that did, or did not, do that.
How the Structure Interacts With E-2 Visa Eligibility
The E-2 route through acquisition
For many European buyers the acquisition is also the platform for an E-2 treaty investor visa, available to nationals of treaty countries, Italy among them, who make a substantial investment in a U.S. enterprise they develop and direct. Buying an operating business can be a strong E-2 foundation precisely because the enterprise is demonstrably real and non-marginal from day one.
What the visa case needs from the deal
The E-2 requirements reach into the deal’s structure: the treaty-national buyer must hold the required ownership and control, the funds must be genuinely committed and at risk, and the paper trail, source of funds, purchase documents, corporate structure, becomes the evidentiary core of the visa filing. Deal features that make commercial sense can complicate the visa case, and structures exist that satisfy both, but only when the immigration filing is designed together with the acquisition rather than after it. For a buyer who is also relocating, the closing checklist and the visa checklist are one document.
Why Financial Due Diligence Alone Is Not Enough
Financial diligence answers whether the numbers are real. It does not answer whether the contracts survive the sale, whether the trademark is owned, whether the workforce is properly classified, whether the landlord will consent, or whether the structure supports the buyer’s visa, and those questions sink acquisitions that the numbers approved. The financial and legal reviews are parallel workstreams on the same timeline, and a foreign buyer should treat a deal team without the legal half as a deal team missing half.
Where an International Business Law Attorney Fits
A cross-border acquisition runs on two tracks that have to stay synchronized: the U.S. legal work, diligence, structure, purchase agreement, closing, and the buyer’s own side, corporate approvals at home, funds flowing across borders, and often an immigration strategy riding on the deal. Running those tracks separately puts the buyer in the middle, translating between advisors while the exclusivity clock runs.
This is the specific value of an international business law attorney built for the cross-border corridor. Di Martino Law Group conducts acquisition due diligence for foreign buyers end to end, corporate, contracts, liabilities, leases, and intellectual property, structures the purchase on the corporate and contract law side, and aligns the deal with the buyer’s E-2 or other immigration strategy in the same engagement, working in English and Italian from Los Angeles. For European buyers, and Italian buyers in particular, working with a corporate attorney in Los Angeles who is also an Italian corporate lawyer means the U.S. findings are understood at home as clearly as they are found here, with the firm coordinating as an international law corporation counterpart with the buyer’s home-country counsel where the deal requires it.
Buying With Eyes Open
An acquisition is the fastest route into the U.S. market and the fastest way to inherit someone else’s problems, and due diligence is what separates the two. The foreign buyers who acquire well are the ones who let the structure follow the findings, read the contracts before pricing the revenue, verified ownership before valuing the brand, and built the visa case into the deal rather than after it. Every item on this checklist costs less than the smallest problem it prevents.
If you are considering acquiring a U.S. business, the right time to start the legal review is before the letter of intent is signed. Contact Di Martino Law Group for a business acquisition due diligence consultation.